Life Insurance in UAE
Life insurance in the UAE pays your nominee upon your death while the policy is active. UAE residents can buy AED 1,000,000 life cover for AED 50–AED 82 per month, depending on age and health status. You can also compare 35+ CBUAE-accredited insurers on policybazaar.ae.
4.7/5
46,418
 Reviews
Central Bank UAE Registration No.: - 123
Insurance Partners
Trusted Customers
Policies Sold
Starting @ AED 50/month*


 Qualified Policybazaar expert will assist you
 Aashima Mongia


What is Life Insurance in UAE?
8 Best Life Insurance Plans in UAE (2026 Comparison)
| Plan name | Features | Apply |
|---|---|---|
| HAYAH Term Life Protect |
 Best For: Affordable, high-coverage term protection
Death benefit: AED 1 Million — Accident & Sickness from Day 1
Add-ons
|
|
| MetLife Live Life Now |
Best For: Comprehensive protection with value-added benefits
Add-ons & Benefits
|
|
| Sukoon Life Guard |
Best For: Variable plans with multiple add-on options
Add-ons Available
|
|
| Arabia Term Life |
Best For: Basic life cover with essential riders
Available Riders
|
|
| Zurich International Term Assurance |
Best For: Global coverage with strong brand reliability
Death benefit: AED 1 Million — Accident & Sickness
Add-ons
|
|
| LIC International Life Protect Term Plan 278 |
Best For: Long-term coverage with flexible tenure
Policy Coverage
|
|
| Takaful Emarat Fixed Term Plan |
Best For: Sharia-compliant life insurance
Death benefit: AED 1 Million — Accident & Sickness
Add-ons
|
|
| Arabia Term Life Executive 1 |
Best For: High-net-worth individuals needing large coverage
Add-ons
|
Directly from Experts
Our mission is to help you protect your family’s well-being with affordable life insurance. We strive to make your experience hassle-free to the greatest extent possible, whether you are purchasing a policy or making a claim.If you are thinking about buying life insurance in 2026, it might be a good idea to purchase it as soon as possible.For instance, a 30-year-old man can buy AED 1,000,000 in life cover for AED 58 per month as a non-smoker with HAYAH. The same cover would cost him almost double when he turns 40. Based on our research, the average 25-35-year-old in the UAE saves AED 15,000-AED 20,000 by buying life insurance between the ages of 25 and 35 instead of waiting until age 40. It is never too early to secure your family's future!
 Atul Kathuria Business Head - Term Life Insurance
15+ years in UAE Life Insurance
Why UAE Expats Need Life Insurance (3 Reasons Others Miss)
- 1
Visa Issues
Family members' visas may depend on the working person. - 2
Outstanding Loans
Home loans, personal loans, or credit card debts may still need to be paid. - 3
Travel Costs
Sending a loved one back to their home country can be expensive.

Regulation and Trust: The Role of the Central Bank

Central Bank of the UAE (CBUAE)
- E
Emirates Insurance Federation
Quick Comparison: Best Life Insurance Dubai
| Plan | Best for | Key Benefits |
|---|---|---|
| HAYAH Term Life Protect | Best forAffordable protection | Key BenefitsLow-cost, high cover |
| MetLife Live Life Now | Best forAll-in-one benefits | Key BenefitsHealth + life combo |
| Sukoon Life Guard | Best forFlexibility | Key BenefitsMultiple add-ons |
| Arabia Term Life | Best forBasic cover | Key BenefitsSimple & clean |
| Zurich Term Assurance | Best forExpats | Key BenefitsGlobal coverage |
| LIC International Plan | Best forLong-term | Key BenefitsFlexible tenure |
| Takaful Emarat | Best forIslamic plans | Key BenefitsSharia-compliant |
| Arabia Executive 1 | Best forHigh coverage | Key BenefitsPremium segment |
UAE Life Insurance Market Size & Statistics 2026
 USD 2.54B → 3.02B Market size, 2026 → 2031 Combined life + non-life premiums (≈$17.7B in 2024).
 AED 65.1B → 75.2B Total premiums, 2024 → 2025 UAE life & annuity insurance market, growing at a 3.53% CAGR.
 36.12% Unit-linked plans, fastest-growing Projected through 2031, driven by investment-linked benefits.
 USD 2.54B Regular premium plans Most UAE residents pay monthly/annually rather than lump-sum.
 USD 2.54B Whole life market share Largest product category by premium share in 2025.
 USD 2.54B Digital platform growth More UAE residents comparing and buying life insurance online.
How Much Life Insurance Cover Do You Need in UAE?
Debt
Income
Mortgage
Education
Example: How to use DIME method if you earn AED 15,000/Month
- D Debt Personal loan AED 80,000 + car loan AED 60,000 AED 140,000
- I Income Personal loan AED 80,000 + car loan AED 60,000 AED 2,700,000
- M Mortgage Personal loan AED 80,000 + car loan AED 60,000 AED 800,000
- E Education Personal loan AED 80,000 + car loan AED 60,000 AED 400,000
How to Claim Life Insurance in the UAE?
- 1

Call Us
Speak to our dedicated claims support team at 800 800 001. Advisors are available daily from 8 AM to 11 PM GST. - 2

Email Us
Send your claim details and supporting documents to care@policybazaar.ae — our team will get back to you promptly. - 3

Complete the Claim Form
Add the correct details in the claim form. Make sure it matches the insurance policy exactly. - 4

Submit Required Documents
Death certificate, Emirates ID or passport copy, medical reports (if required), bank details, nominee ID proof. - 5

Submit Your Claim Online
Visit the Policybazaar.ae website and use the “File a Claim” option to start your request online. - 6

Claim Payout
Your nominee receives the money in their bank account or by cheque after claim approval. - 7

Get End-to-End Claims Assistance
Our experts guide you through documentation, coordinate with the insurer, and support you until it’s settled.
What are the Different Types of Life Insurance Policies?

Term Insurance
Term insurance is pure protection. It covers you for a fixed period (10, 20, or 30 years). If you survive the term, there is usually no payout. On the flip side, the premiums are the most affordable.
Whole Life Insurance
A Whole life plan gives you protection for your entire life. It combines protection with a savings component that builds “cash value” over time. Buy if you are planning your legacy.
Unit-Linked Insurance Plans (ULIPs)
In ULIPs, a part of your premium goes to insurance. The other part is invested in global stock markets. This plan is for people with a higher risk appetite looking for market-linked growth.
Endowment Plan
Endowment plan is a structured savings plan that pays a guaranteed lump sum at maturity or a death benefit if you pass away.
Retirement Plan
This type of life insurance in the UAE offers you financial stability once you retire. When you invest in such a plan, you can create a steady income flow during the retirement years.
Savings and Investment Plan
This plan lets you turn your savings into long-term investments. Such plans offer both life insurance coverage and assured maturity benefits.
Importance of Life Insurance at Different Age Group
-
Early 20s
Lock in the lowest possible premiums. Build a foundation before marriage. -
30s – 40s
Peak responsibility years: get cover for spouse, kids, and growing home loans. -
40s – 50s
Focus on wealth growth and post-retirement income planning. -
50+ Years
Focus on leaving a legacy for grandchildren and estate planning.
Features of Best Life Insurance in UAE
Financial Protection
A life plan provides financial security to your family in your absence. If you pass away during the policy term, the nominee receives the sum assured to support their financial needs.
Wealth Creation
Plans like savings, endowment, or ULIPs help you build wealth while offering sufficient life coverage. If you outlive your policy period, the corpus becomes your maturity benefit. AED
Assured Returns with Savings Plans
Savings and retirement plans offer guaranteed returns at maturity. You get the amount in lump sum once you outlive the policy.
Low Premiums for Young Individuals
Buying life cover at a younger age means lower premiums. Younger individuals are less vulnerable to health issues, making them low-risk life assureds.
Lifetime Coverage
With the best life insurance in Dubai, you get lifelong coverage for yourself and your family.
What is the Difference Between Life Insurance and Term Insurance?
| Parameter |  Life Insurance VS |
 Term Insurance |
|---|---|---|
 Death Benefits |
Life Insurance  Yes |
Term Insurance Yes |
 Cash Value |
Life InsuranceYes — fixed or grows over time | Term InsuranceNo |
 Policy Period |
Life InsuranceUsually the entire life or up to the age of 100 years | Term Insurance5 to 35 years |
 Premium |
Life InsuranceHigher due to investment component | Term InsuranceLower |
 Maturity Benefits |
Life InsuranceAs per the policy | Term InsuranceNone |
What Makes Your Life Insurance Premium Higher in UAE?
| Factor | How it affects your cost |
|---|---|
| Age Affects risk profile | Younger individuals usually get lower premiums because they are considered healthier and less likely to develop serious medical conditions. As age increases, the chances of health complications and mortality rise. This increases the cost of insurance. |
| Lifestyle Habits | Smoking, tobacco use, or heavy alcohol consumption can lead to much higher premiums. These lifestyle choices increase the risk of illnesses such as cancer, heart disease, and liver complications, making the policyholder a higher-risk applicant. |
| Medical History | A history of heart disease, cancer, or chronic conditions increases the risk profile and costs because they indicate a higher risk of future claims. |
| Policy Term | The longer the policy duration, the higher the premium. This is because the insurer provides protection for a longer period, increasing the probability of a claim payout during the policy tenure. |
| Occupation Type | Individuals working in high-risk professions such as construction, aviation, offshore oil & gas, mining, or armed services may pay higher premiums because of increased accident or health risks associated with these jobs. |
| Add-ons & Riders | Adding extra protection benefits such as critical illness cover, accidental death cover, waiver of premium, or disability riders increases your premium because they expand the scope of coverage. |
Life Insurance vs Other Savings Products: Which One Should You Choose?
| Feature | Life Insurance | Investment |
|---|---|---|
| Risk Coverage | Includes life cover and protection benefits | Usually does not provide life coverage |
| Returns | Offers stable and relatively safer returns depending on the policy type | Returns may vary based on market conditions and investment type |
| Investment Component | Some plans like ULIPs and endowment plans combine insurance with investment | Purely investment or savings-focused |
| Maturity Benefits | Certain plans provide maturity or survival benefits | Returns depend entirely on investment performance |
| Liquidity | Limited liquidity during the policy term | Many savings products offer easier access to funds |
| Discipline in Saving | Regular premium payments encourage disciplined long-term savings | Depends on individual investment habits |
What is Covered & Not Covered in Life Insurance UAE?

What’s Covered
7 benefits-
If the insured person passes away during the policy term, the nominee receives the sum assured as a lump sum payout.
-
Deaths caused by illness, health conditions, or natural causes are generally covered under the policy.
-
Many plans offer an additional payout if death occurs due to an accident such as a road accident or workplace injury.
-
With a critical illness rider, the insurer pays a lump sum if diagnosed with illnesses like cancer, heart attack, or stroke.
-
Some policies provide you with financial support if the insured becomes permanently disabled and cannot work.
-
You can choose some optional riders that may provide daily cash benefits during hospitalisation to cover extra expenses.
-
Optional riders may provide daily cash benefits during hospitalisation to manage extra expenses.

What’s Not Covered
7 exclusions-
If a person hurts themselves and dies within the 12 months of buying the insurance, the insurance company may not pay the money.
-
If someone dies while doing something against the law or driving after drinking alcohol, the insurance company may not pay.
-
If a person intentionally hurts themselves and dies because of it, the insurance company may not cover it.
-
Some insurance plans may not pay if a person dies because of war, terrorism, or serious public violence.
-
Some policies exclude coverage for death or injury resulting from war, acts of war, or terrorism-related incidents.
-
If a person dies because of taking too many drugs or drinking too much alcohol, the insurance company may not cover it.
-
Providing false information or attempting to cheat the insurance company may result in the claim being rejected.
3 Expert Tips to Buy Life Insurance Cheaper in UAE
-
 01
Compare Online
Use platforms like Policybazaar.ae to compare 30+ plans for free. Online policies are often cheaper than offline ones. -
 02
Check the CSR
The Claim Settlement Ratio tells you how many claims the company has successfully paid. -
 03
Read the Document
Always spend at least 5-10 minutes reading the exclusions to avoid surprises later.
Online vs Offline Life Insurance
| Feature | Online | Offline |
|---|---|---|
 Lower Premiums |
 Yes |
 Usually No |
 Convenience |
High |
 Limited |
 Easy Comparison |
High |
Limited |
 Digital Support |
High |
Limited |
 Customization |
Better |
Moderate |
 Transparency |
Higher |
Depends |
Do's and Don'ts of a Life Insurance Policy
DO'S
- ✓Buy early
- ✓Compare plans
- ✓Read policy documents carefully
- ✓Choose suitable riders
DON'TS
- ×Hide smoking or medical history
- ×Delay policy purchase
- ×Miss premium payments
- ×Underinsure yourself
Eligibility Criteria to Buy a Life Insurance Policy in UAE
 The potential policyholder should fall within the age bracket of 18 to 75 years to be eligible for a life cover policy.
- It's necessary for the applicant to demonstrate a stable and reliable stream of income.
- The individual applying for the plan should be a resident of the UAE and possess all the requisite documentation.
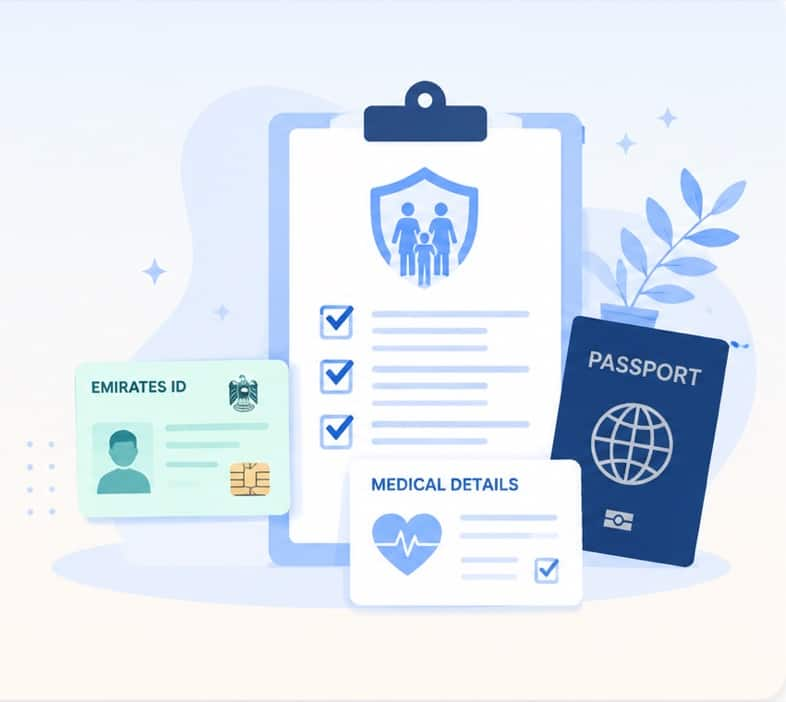
Documents to Apply for Life Insurance UAE
 Emirates ID
- Passport or UAE residence visa (for expats)
- Medical details
How to Buy Life Insurance from Policybazaar.ae?
-
01
Step 1: Assess Your Financial Needs
Start by understanding:- How much life cover your family may need
- Your current income and liabilities
- Existing loans or future financial goals
- The policy term you require
This helps you choose the right sum assured and policy type. -
02
Step 2: Compare Life Insurance Plans
Visit Policybazaar.ae and compare different life insurance plans from leading insurers in the UAE. You can compare- Premiums
- Coverage amount
- Policy term
- Riders and add-ons
- Claim benefits
- Investment or savings options, and much more
-
03
Step 3: Fill Basic Details
Provide basic information such as your age, nationality, income, smoking habits, employment details, and coverage requirement. This helps generate personalised quotes. -
04
Step 4: Choose the Right Policy
Select the policy that best matches your- Budget
- Family responsibilities
- Future goals
- Risk profile
You can also add riders like- Critical illness cover
- Accidental death benefit
- Disability cover
- Waiver of premium
-
05
Step 5: Submit Documents
- Emirates ID or Passport
- Visa copy
- Income proof
- Medical reports (if required)
Some insurers may also request a medical check-up. -
06
Step 6: Make Payment
After approval, pay the premium online using a secure payment method and get your policy. Share the policy documents digitally. Coverage becomes active as per policy terms.
Why Buy Life Insurance in UAE Through Policybazaar.ae?
 This makes choosing the right life insurance plan in the UAE simpler and more convenient.
- 01 Compare plans from multiple insurers in one place
- 02 Get expert assistance at no extra cost
- 03 Fast and simple online application process
- 04 Customised plan recommendations
- 05 Transparent comparison of premiums and benefits
- 06 Dedicated customer support during purchase and claims
Why are Riders Important in UAE Life Insurance?
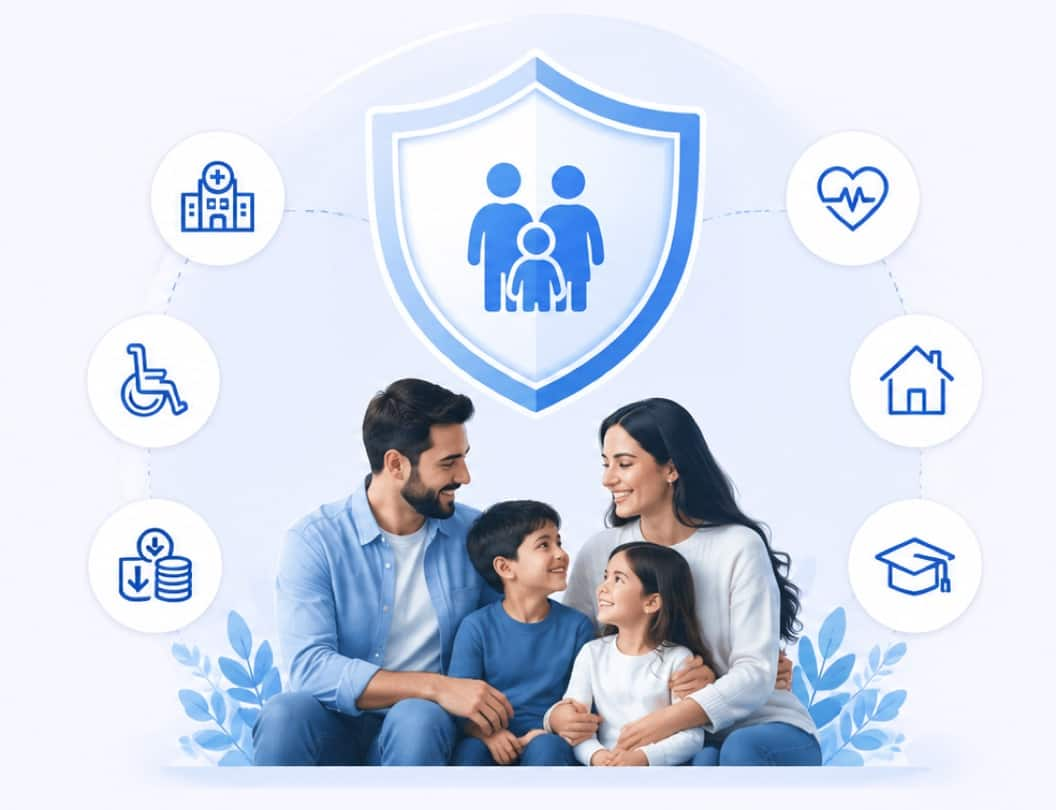
 Medical emergencies
- Disabilities
- Critical illnesses
- Family living expenses
- Children’s future expenses
What are the Riders for Life Insurance Policies?
-
01
Critical Illness
This benefit comes into play when the life assured is diagnosed with any of the critical illnesses covered and mentioned in the underwriting. In this case, a lump sum amount is paid to the life assured. This sum can be used for treatment, compensating for the loss of income during the treatment period, daily expenses, and more. -
02
Accidental Death
In case of accidental death, the life assured's family is paid an additional amount along with the pre-determined sum assured. However, keep in mind that the policyholder must have bought this rider at the time of policy purchase. -
03
Waiver of Premium in Case of Disability
If the insured becomes incapable of paying future premiums due to a disability, the premiums will be waived and the policy will remain active. -
04
Terminal Illness
In case the life assured gets diagnosed with a terminal illness that cannot be cured and can result in death within one year (the time can vary from plan to plan), the company will pay the applicable benefit as per the policy underwriting. -
05
Second Medical Opinion
Several life insurance policies in the UAE offer a second medical opinion rider. With this benefit, the life assured can get a second medical opinion from renowned healthcare centres, usually for free. -
06
Permanent and Total Disability
If you buy this rider during policy purchase, the insurance company pays an assured amount (predetermined during the purchasing process) in case you become permanently totally disabled because of an accident or sickness.
What is the meaning of sum assured?
Sum assured is the assured amount that the policyholder will receive. It is also known as the coverage amount for which an individual is insured.
Is it expensive to buy the best life insurance policy in UAE?
There is a wide range of life cover UAE options that work for every budget and financial situation. Thus, it is best to shop around and compare different life insurance quotes online based on the coverage, features, and price in order to find best insurance policy as per your insurance needs and convenience.
What happens if you do not pay the premium on time for your life insurance policy?
If you miss a life insurance premium payment in the UAE, your policy may enter a grace period (typically of 30 days). However, if you fail to pay even within this time, your policy lapses and you lose the coverage and other benefits until reinstatement.
Will you be covered by your life insurance if you have a pre-existing medical condition?
Yes, you are covered even if you have a pre-existing medical condition; you would be charged with a loading.
Do you need to go for a medical examination if you buy a life insurance plan?
Yes, you would need to undergo a medical examination, but only if you are in your 40s and buying life cover. The reason behind a medical examination is to know if you have any medical condition developing. The coverage and premium is decided accordingly.
How much life insurance cover do you need?
Your life cover should be at least 10 times your annual income. The sum assured the beneficiary will receive can be used to pay off debt, higher education, create an emergency fund, and more.
Is Life Insurance Mandatory in UAE?
Life insurance is not mandatory in the UAE for individuals, unlike health insurance. However, many UAE banks require life insurance (also called mortgage protection) if you take a home loan. Employers may provide group life cover, but individual cover is your own responsibility.
Top Life Insurance Providers






Everything You Need to Know About Life Insurance

More From Term Insurance
- Recent Articles
- Popular Articles
 Last Updated : 12 Nov 2026Term Insurance Benefits in UAE: 8 Key AdvantagesExplore 8 term insurance benefits in the UAE: high cover at low premiums, loan protection, riders and worldwide cover. Compare plans on Policybazaar.ae.
 Last Updated : 04 Nov 2026Is Life Insurance Payout Taxable?Life insurance payouts aren't taxed in the UAE, but Indian policies follow Indian tax law. See NRI rules for death, maturity and ULIP payouts, TDS and DTAA.
 Last Updated : 04 Nov 20268 Benefits of Life Insurance in UAE for Residents & ExpatsDiscover 8 benefits of life insurance in the UAE, from income replacement and loan protection to children’s education and riders. With AED examples.
 Last Updated : 11 Nov 2026Smart Return Term Plan UAE: Premium Refund & TROP ComparisonAlliance’s Smart Return Term Plan refunds base premiums via the Smart Exit Benefit on 30-year policies. See eligibility, exclusions and how it compares with TROP.
 Last Updated : 15 Oct 2026Term Insurance Maturity: Benefit, Value & What Happens (UAE)Does term insurance have maturity benefit? See the meaning, why pure term plans pay no maturity value, return-of-premium options, and what to do when cover ends.
- Last Updated : 15 Oct 2026Life Insurance Maturity Benefit: Meaning, Value & Payout UAELife insurance maturity explained for UAE policyholders: maturity date vs benefit, maturity value vs surrender value, the maturity period, tax and the claim process.
 Last Updated : 12 Nov 2026Top Life Insurance Companies in Dubai, UAE 2026 | Compare Top ProvidersCompare top 10 life insurance companies in UAE , Zurich (98% CSR), MetLife, HAYAH & more. CBUAE-licensed. Get instant quotes. Explore top providers and choose a plan that fits your needs.
 Last Updated : 26 Aug 2026Term Insurance for Self-Employed in UAE 2026 | From AED 50*/MonCompare the best term insurance plans for self-employed individuals in UAE. No employer cover? Secure AED 1M life cover from AED 50/month. Get free quotes now.
 Last Updated : 02 Oct 2026Term Insurance for NRI | Best Term Insurance Plan for NRI in UAETerm Insurance for NRI - Compare and Buy best term insurance policies for NRI in UAE & know important things before buying the term plan for NRI in UAE.
 Last Updated : 23 Mar 2026Term Insurance for Spouse in UAE - Features & BenefitsTerm Insurance for Spouse - Choose the best term insurance plan for your spouse in UAE with features & Benefits. Also, know who can buy a spouse term insurance plan.
 Last Updated : 12 Dec 2025Top Life Insurance Plans for Expats in the UAE: Protect Your Family's FutureDiscover the best life insurance options for expatriates in the UAE. Learn about key benefits, top plans, and essential tips to secure financial protection for your loved ones.
 Last Updated : 19 Sep 2025Short Term Disability Insurance | Benefits & How It WorksDiscover short term disability insurance options to safeguard your income during challenging times. Get affordable coverage tailored to your needs!


 Reviews